Businesses are paying closer attention to payment fraud, but it’s becoming clear that awareness alone is not enough to keep fraudsters at bay, with many organizations still lacking the processes, training and technology required to safeguard their finances.
New local research commissioned by Eftsure found that 55% of US respondents feel more exposed to financial fraud than they did 12 months ago, while 59% do not feel fully prepared to identify modern payment scams. Worryingly, just 33% said they had received clear, practical training on preventing payment fraud.
For business leaders, closing this gap means looking beyond cybersecurity tools to the everyday decisions, workplace behaviors and processes that determine where the money ends up.
AI is raising the stakes, but the fundamentals still matter
AI is making it easier and cheaper for fraudsters to create convincing messages and impersonate trusted contacts to make fraudulent requests appear legitimate, with Eftsure finding that 76% of respondents expressed concern about AI-assisted scams, including fake invoices and AI-generated fraud attempts.
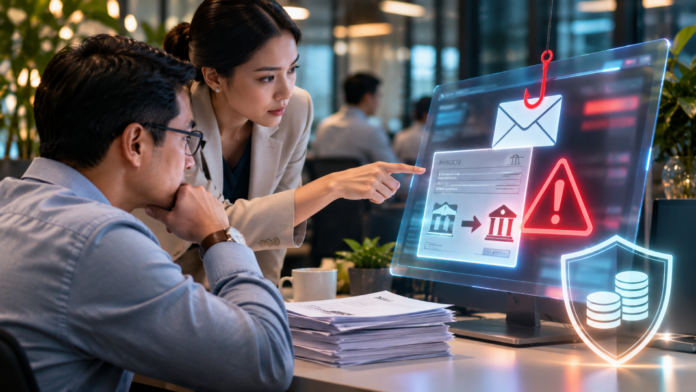
However, just focusing on the technology behind these attacks can minimise why they succeed in the first place. Relatively inconspicuous situations such as vendors receiving emails advising of changed bank account details or capitalising on rushed employees pushing through an urgent wire transfer request from someone claiming to be a senior executive are now firmly part of the playbook for cybercriminals.
It’s important here to clarify that the answer is not to expect employees to identify every scam by sight. Instead, businesses need payment processes that don’t rely solely on someone recognizing suspicious activity: that means independent verification, clear approval procedures and consistent checks, all of which can prevent fraudulent requests from becoming costly mistakes.
When workplace culture becomes a fraud risk
Even the greatest payment controls in business are only effective when employees feel empowered to actually use them.
Eftsure found that 72% of respondents did not fully believe their senior leaders understood how modern payment fraud occurs or its potential impact. Meanwhile, only 31% felt completely comfortable questioning or challenging a payment request from a senior colleague.
Employees hesitating to question an urgent request from an executive are operating within a workplace culture that’s holding the door open for fraudsters. Leaders need to make it clear that challenging unusual payment instructions is a responsibility, not an inconvenience: employees should be encouraged to raise concern with clear escalation procedures without fear of repercussions.
Make verification part of everyday operations
One concerning finding of the research relates to changes in banking details, with nearly one in three respondents (29%) unsure what steps their organization should take when a vendor requests new bank details. On top of this, only 35% said their organization independently verifies these requests by calling the vendor using a trusted phone number.
Businesses should require changes to these details to be confirmed independently using contact information already on file, rather than details provided in the request. Unusual or significant payments should receive appropriate additional approval, and responsibilities for onboarding vendors and authorizing payments should be clearly defined.
Verification should be a standard part of the accounts payable process, not something employees undertake only when a request seems suspicious.
Ultimately, payment fraud cannot be addressed through awareness campaigns or technology in isolation. It requires people who understand the risks, processes that make verification routine and systems that provide additional assurance before money moves.
The goal should be to build payment processes that remain resilient even when a convincing fraudulent request slips through.
Join our LinkedIn group Information Security Community!